Does homeowners insurance cover a leaking skylight?
By Priya Vogel, Editorial Lead · Updated 2026-11-03
When a skylight leaks into a ceiling, the first question is usually who pays. There is no single answer, since coverage depends on your policy and the cause of the damage. What you can do is understand how insurers tend to think about it and gather the right evidence.
The core distinction
Insurers generally separate sudden damage from gradual deterioration. A storm that cracks a dome or tears flashing is treated differently from a seal that aged out over fifteen years. Many policies exclude wear and tear, and some exclude damage that built up over time. Others cover sudden, accidental events. Your policy wording controls.
| Situation | How it is often viewed |
|---|---|
| Storm damage to the unit or roof | May fall under covered wind or storm perils, subject to deductibles |
| Slow leak from aging flashing | Often treated as maintenance or wear |
| Interior water damage after a sudden event | May be covered separately from the skylight |
| Leak from poor past installation | Can be disputed; the contractor’s warranty may matter |
| Fogged glazing | Typically a wear item |
Treat that table as a rough orientation, not a prediction. Deductibles in Florida, including separate hurricane deductibles, can change the math.
What to do right away
- Stop the damage: containers, tarps, moved belongings.
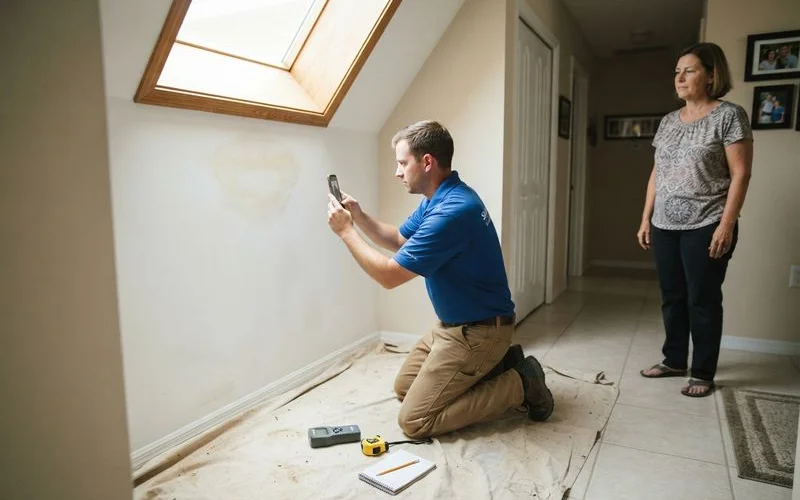
- Photograph the ceiling, shaft, and unit, and note the date and weather.
- Read your policy’s sections on water damage and roof coverage.
- Call your insurer or agent and ask what they require before repairs.
- Keep receipts for emergency measures.
What documentation helps
A written report from a licensed contractor describing the cause is the strongest piece you can add. Ask them to describe what failed, where, and likely when. Also keep the original installation paperwork, warranty, and permit record if you have them. A past warranty may cover the installer’s labor even when insurance does not.
Where contractors fit
Reviewers of local businesses often mention honest estimates and fast response to calls and leaks. For an insurance matter, that matters: you want a contractor who writes down what they found rather than guessing. Be wary of anyone who promises to get a claim approved. Nobody can promise that, and a contractor should not act as your insurance advocate.
Wear versus storm: why it matters
If the cause is wear, repair or replacement is generally your cost, so compare quotes carefully. See the skylight repair and leak category for local businesses, and read our rubric for how we evaluate them. The home page lists everything else. If you are still working out what failed, why skylights leak lists the usual causes.
Keep it factual
When you speak to the insurer, describe what you saw, not what you assume. Dates, photos, and plain descriptions work better than guesses about cause.
If the claim is denied or limited
A denial is not always the end. Ask the insurer to explain the reason in writing and which policy provision applies. You can request a review, supply the contractor’s report, or consult a licensed public adjuster or attorney for your situation. Keep deadlines in mind, since policies and Florida rules set time limits for reporting and for disputing claims. Check yours rather than assuming.
This is general information, not insurance or legal advice. Coverage depends on your specific policy, so confirm with your insurer or a licensed agent.
Questions people ask
- Will insurance pay to replace a worn-out skylight?
- Policies commonly exclude wear, age, and deterioration. Whether yours covers the unit depends on the cause of the damage and your exact policy wording.
- Is water damage inside covered even if the skylight is not?
- Sometimes. Coverage for resulting interior damage can differ from coverage for the skylight itself. Your policy and your insurer decide, so ask.
- Should I fix the leak before the adjuster visits?
- Take steps to prevent further damage and keep receipts, but photograph everything first and ask your insurer what they require before repairs.
- Does a roofing contractor's estimate help a claim?
- A written inspection report that names the cause can be useful documentation. It does not guarantee coverage.